Rep. Hakeem Jeffries and House Democrats are preparing legislative strategies to dismantle Trump's tariff regime once they regain congressional control, signaling an immediate policy clash on trade. The party is framing tariffs as a driver of consumer price inflation, particularly on gasoline and manufactured goods, positioning rollback as an affordability solution.
Key points
Market impact. Tariff uncertainty will keep equity volatility elevated, particularly in industrials, consumer discretionary, and energy sectors that face input cost pressures. Investors should monitor congressional composition shifts and Trump's tariff implementation timeline—broad tariffs could suppress earnings growth across S&P 500 companies already posting razor-thin earnings beats.
Broader implications. This signals a structural policy gridlock ahead: Trump's protectionist agenda versus Democratic free-trade preferences will define fiscal and trade policy for the next two years, creating persistent macro uncertainty and potential supply-chain disruptions.
Sources (3)CNBC Top Stories, New York Post Business, Market Watch
Neutral +62 sourcesnvidia · china · export controls
The Commerce Department cleared dozens of Chinese companies to purchase Nvidia H200 chips, including firms operating from empty offices and entities with troubling financial or operational ties. The approvals represent a significant gap in U.S. export control enforcement against advanced semiconductor technology destined for China.
Key points
Market impact. This undermines the credibility of U.S. semiconductor export restrictions and could trigger congressional scrutiny, potentially tightening controls further and reducing Nvidia's addressable market in Asia. Nvidia shares may face pressure if regulators impose stricter vetting or volume caps on China sales going forward.
Broader implications. The lapse exposes weaknesses in the Biden administration's China tech containment strategy and invites Republican criticism on national security grounds, likely accelerating Trump-era restrictions on semiconductor exports and AI chip distribution to adversaries.
Neutral 01 sourceearnings · wall street · profit margins
Corporate America is posting earnings beats against Wall Street expectations, but by the slimmest margins in roughly four years, signaling tightening profit conditions and limited upside surprise potential. The compressed beat rate reflects both analyst conservatism and genuine earnings pressure across the S&P 500.
Key points
Market impact. Narrow beats reduce the catalyst for equity rallies and increase downside risk if companies issue cautious guidance. Valuations remain elevated on historical earnings multiples, leaving limited margin for disappointment—any miss could trigger sharp selloffs in individual names and sector rotation toward defensive plays.
Broader implications. This earnings dynamic reflects macro headwinds: tariff uncertainty, labor cost inflation, and geopolitical risk are compressing margins, making 2025 earnings growth dependent on cost-cutting and operational efficiency rather than revenue expansion.
Nvidia, AMD, and broader semiconductor equities are recovering from a sharp selloff in the AI trade, though analysts caution that underlying volatility drivers remain unresolved. The rebound reflects short-covering and technical support rather than fundamental catalyst resolution.
Key points
Market impact. Chip sector volatility will persist as long as AI capex spending remains uncertain and geopolitical export controls loom. Nvidia's valuation premium is vulnerable to any signal of slowing data center demand or tighter China restrictions; AMD and other competitors may outperform if diversification narratives gain traction.
Broader implications. The AI trade's volatility reflects investor uncertainty about sustainable returns on massive data center buildouts and whether current capex cycles justify current valuations—a structural question that will define tech sector performance through 2025.
Bullish +281 sourceanthropic · ai infrastructure · capex
Anthropic has locked in a $3.4 billion deal for power generation infrastructure and engineering services to support massive AI data center deployments, signaling aggressive buildout plans and addressing the critical power bottleneck constraining AI model training and inference at scale.
Key points
Market impact. This deal benefits power infrastructure suppliers, construction firms, and energy companies while validating the capex intensity thesis driving semiconductor and data center equipment demand. It also signals that AI companies are moving beyond chip procurement into full-stack infrastructure control, potentially reducing dependency on cloud providers like AWS and Azure.
Broader implications. The deal underscores that power availability and grid capacity are now the binding constraint on AI scaling, not chip supply—a shift that will reshape energy markets and accelerate demand for both renewable and dispatchable generation capacity.
Strong bearish −791 sourcestock correlation · market signal · volatility
Correlations between individual stocks have hit record lows, indicating extreme market fragmentation where individual names are moving independently of broad indices and sector peers. This metric previously signaled the onset of the recent tech selloff and is now flashing another warning.
Key points
Market impact. Low correlations typically precede mean reversion—a period where diversification benefits evaporate and broad-based selloffs accelerate. Investors holding concentrated positions or relying on sector rotation strategies face elevated drawdown risk if correlations snap back toward historical norms.
Broader implications. The fragmentation reflects divergent earnings trajectories, geopolitical exposures, and policy sensitivities across the market; a reversion would suggest either a broad rally or a synchronized decline, neither of which appears imminent given macro uncertainty.
Escalating Iran-related geopolitical risk has driven oil prices higher, creating a secondary shock to housing affordability through elevated transportation and construction costs. The impact extends beyond gas prices to the full cost structure of homebuilding and mortgage servicing.
Key points
Market impact. Higher oil prices compress homebuilder margins and reduce demand for new construction, pressuring stocks like Lennar, D.R. Horton, and Toll Brothers. Mortgage rates remain sticky despite Fed rate cuts, and energy cost inflation adds another headwind to housing affordability metrics already at decade lows.
Broader implications. Geopolitical oil shocks are now a structural constraint on U.S. housing recovery; any further Middle East escalation could trigger a sharp contraction in residential real estate activity and consumer spending on discretionary goods dependent on home equity extraction.
Neutral −51 sourceukraine · energy · infrastructure
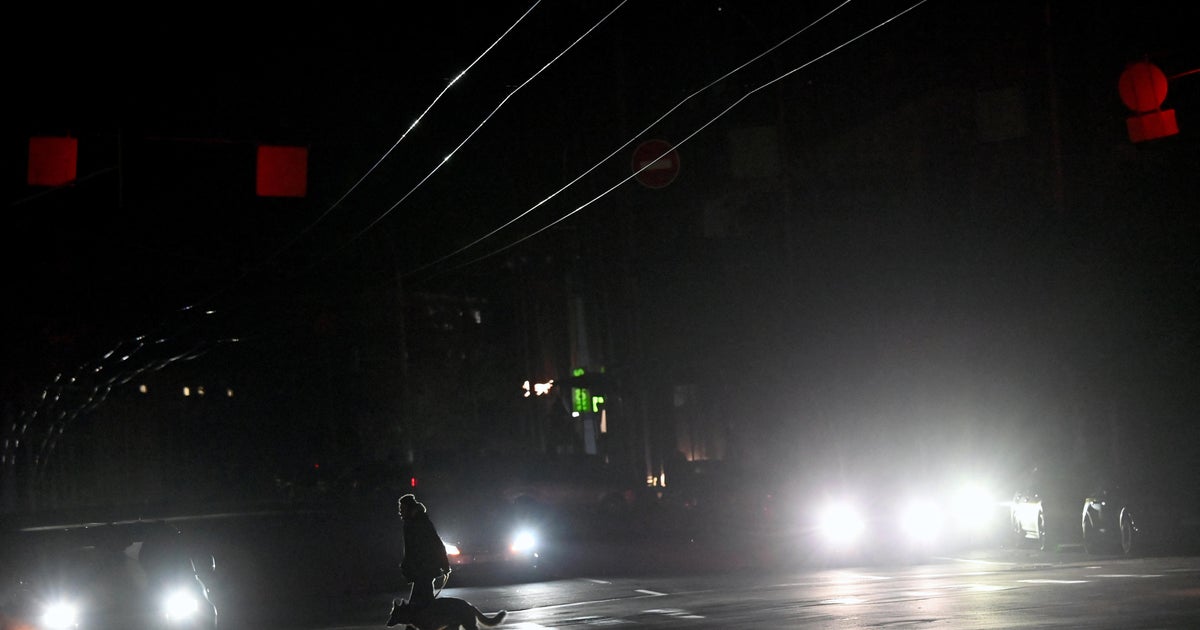
Russia has conducted sustained attacks on Ukraine's energy infrastructure, leaving more than 600,000 people without power as winter weather sets in. The strikes target generation and transmission capacity, creating a humanitarian crisis and signaling Moscow's strategy to degrade civilian morale and economic function.
Key points
Market impact. Continued infrastructure destruction will drive European energy prices higher and increase demand for LNG imports, benefiting U.S. energy exporters and pressuring European industrial competitiveness. Defense contractors supplying Ukraine will see sustained demand for air defense and power restoration equipment.
Broader implications. The winter energy crisis in Ukraine signals that the conflict is entering a grinding attrition phase with no near-term resolution, sustaining elevated European energy costs and geopolitical risk premiums in commodities and equities through 2025.
Neutral 01 sourcesenate · central bank · presidential power
A Democratic Senate majority would represent the broadest institutional check yet on presidential efforts to influence Federal Reserve policy and leadership appointments, limiting Trump's ability to reshape the central bank through personnel changes or political pressure.
Key points
Market impact. Senate composition directly affects Fed Chair and Governor confirmation votes; a Democratic majority would likely block nominees perceived as politically aligned or dovish on inflation. This creates policy uncertainty around interest rate trajectories and monetary tightening cycles, affecting bond yields and equity valuations.
Broader implications. Central bank independence is now a partisan flashpoint; the outcome of Senate control will determine whether the Fed retains operational autonomy or faces sustained political pressure on rate-setting, with profound implications for inflation expectations and long-term asset prices.